On 17 September 2026, The National reports that UAE mortgage rates held steady this year, despite a 75 basis point cut in benchmark rates during 2025.
On this page
In the United Arab Emirates, the cost of money has fallen without mortgage rates following at the same pace. On 17 September 2026, the daily The National reported that UAE benchmark rates dropped by 75 basis points over the course of 2025, yet mortgage rates have remained broadly stable throughout the current year. Three-year fixed rates currently range between 3.89% and 4.24%. The Central Bank of the UAE adjusts its rates in step with the US Federal Reserve, as the dirham is pegged to the dollar — but this monetary mechanism does not automatically translate into the terms offered to borrowers.
Key takeaways
- UAE benchmark rates fell by 75 basis points over 2025, according to The National (17 September 2026).
- In December 2025, the Central Bank of the UAE cut its overnight deposit rate by 25 basis points, to 3.65%, in step with the US Federal Reserve.
- Despite this easing, mortgage rates remained broadly stable in 2026, with three-year fixed rates ranging between 3.89% and 4.24%.
- Salaried employees of established companies with a clean credit history secure the best borrowing terms.
- Self-employed borrowers, new residents and those already heavily indebted face stricter access conditions.
Why mortgage rates aren't following the drop in the cost of money
A cut in benchmark rates does not automatically make mortgages cheaper. Since the dirham is pegged to the US dollar, the Central Bank of the UAE follows the Federal Reserve's decisions: in December 2025, it lowered its overnight deposit rate by 25 basis points, to 3.65%. Yet The National noted on 17 September 2026 that mortgage rates stayed broadly stable this year, with three-year fixed rates moving between 3.89% and 4.24%.
The gap is easy to explain: a fixed rate shields the borrower from a future rise in the cost of money, and banks price in both the cost of risk and their market expectations, not just the current benchmark rate. For an investor, the lesson is clear: benchmark rates set the trend, but the actual monthly payment depends on the product chosen, the bank, and above all the strength of the application.
Featured
View projects: DWTN Residences
From AED 2,271,477
Hand-picked new properties with end-to-end expert support.
View projects
The borrower's profile matters as much as the rate level
At comparable headline rates, access to credit remains highly differentiated by profile. The National stresses that salaried employees of established companies with a clean credit history obtain the best terms, while the self-employed, new residents and already-indebted borrowers run into tighter requirements.
In practical terms, the nature of the employment contract, length of residence in the UAE and existing debt ratio shape the rate obtained, the amount financed, and sometimes whether the application is accepted at all. This is a decisive factor for anyone building a buy-to-let strategy in Dubai: we set out these deposit and eligibility rules in our guide Financing a property purchase in Dubai: mortgage and deposit for non-residents.
What it means for investors
For an investor, this news is a reminder of something too often overlooked: leverage capacity depends not only on the headline rate, but on the profile the bank sees in the application. The same property can be financed on markedly different terms depending on whether the buyer is a salaried employee of a large established group or a recently settled freelancer. Before even targeting a district or a project, we advise clarifying your real borrowing capacity, because that is what determines the acquisition budget and, in turn, the profitability of the deal.
The rate, moreover, is only one line of the financing plan. Dubai Land Department transfer fees, bank arrangement fees, property valuation, insurance: the full budget always exceeds the headline price, as we detail in our guide on the costs of buying property in Dubai. A rate of around 4% remains competitive in a market where individuals pay neither tax on rental income nor capital gains tax on property, which mechanically improves the net return of a leveraged deal.
Our role at Lucretia is to secure that trade-off: assessing your eligibility for local financing, comparing bank offers according to your status, and aligning the financing with your overall wealth strategy. To position Dubai against other markets based on your profile, our analysis Investing in Dubai or Bali sets out the right benchmarks, and our page Investing in Dubai brings together the essentials of the market.
Source: thenationalnews.com — 2026-09-17
Free guide, delivered on WhatsApp
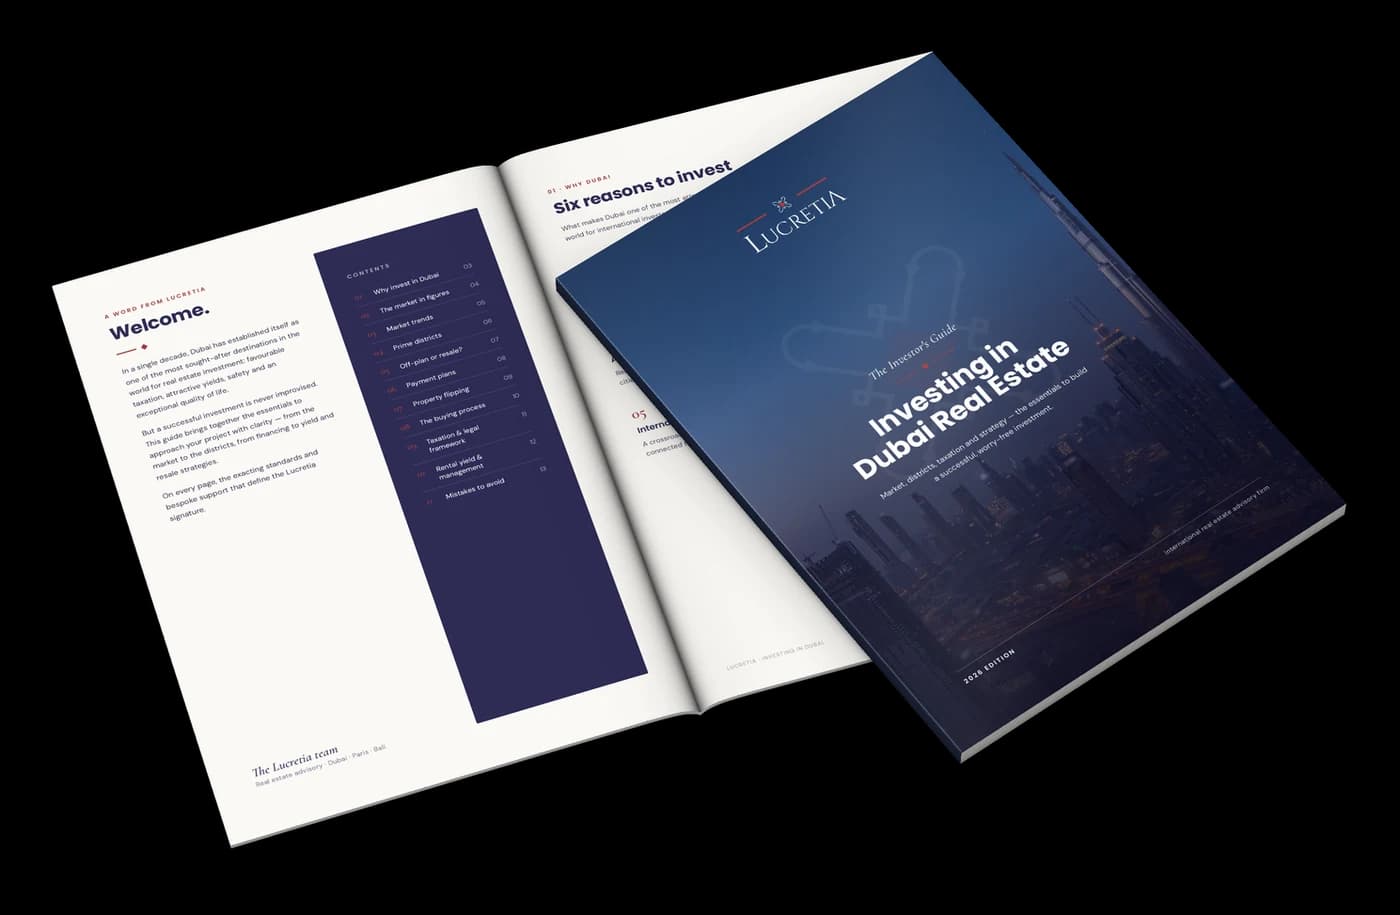
Get the guide "Investing in Dubai"
Taxation, visas, financing, buying steps: 14 pages written by our advisers, sent to your WhatsApp within minutes.
This article is part of our guide
Dubai Property Investment Guide for Foreign Buyers
About the author
Benoit CLAUDEL
Director of Strategy & Operations
With over 18 years of experience in real estate and wealth management, Benoît has developed recognized expertise in advising private investors, business executives and family offices. After starting out in a real estate agency and working within one of the most reputable wealth management firms in Paris, he then joined LCL as Head of Private Banking for Île-de-France, advising high-income clients on their real estate strategies. An entrepreneur, he founded and ran his own wealth management firm for 7 years, structuring investment and wealth optimization solutions. Today at Lucretia, Benoît oversees operational strategy, sales performance and advisor training. He works on high-value-added cases, particularly investments via French holding companies, legal structuring and wealth taxation.