Down payment, bank mortgage, developer payment plan: how a foreign buyer can finance property in Abu Dhabi. A worked example in Al Bahyah follows the deal from the deposit through to rental income.
On this page
- How to finance a property purchase in Abu Dhabi: the three options
- Worked example: financing AED 1.5M in Al Bahyah, from down payment to rent
- Developer payment plan or bank mortgage: which to choose?
- Does leverage pay off? Gross yields versus the cost of borrowing
- Financing a purchase with the Golden Visa in mind
- Where financing fits into the buying process
- The pitfalls of property financing in Abu Dhabi
Getting a mortgage in Abu Dhabi as a foreigner starts with a down payment of at least 20%: the Central Bank of the UAE (CBUAE) caps lending at 80% of the value for a first primary home worth AED 5 million or less, and at 70% above that.
A bank loan is only one of the possible structures. On a new-build property, the developer's payment plan is often more flexible than the bank, and some buyers pay entirely in cash. The right choice depends on the property, the handover date and the rent you expect. The figures below are there for you to run your own numbers.
How to finance a property purchase in Abu Dhabi: the three options
A foreign buyer purchasing in the designated investment zones (Al Reem, Yas, Saadiyat…), open to foreign ownership according to DARI, has three options: their own funds, the developer's payment plan on an off-plan purchase, or a bank loan taken out in the UAE or in their country of residence.
Here are the amounts involved. Among the projects we list, entry prices range from AED 500,000 to AED 2M, with a median of AED 1.5M. These figures cover the 17 projects with a displayable price, out of 69 published in our catalogue.
What is always paid in cash
Whatever the structure, three items are paid in cash on top of your down payment: the transfer fee of 2% of the purchase price, settled via ADREC/DARI, the registration fees and the agency commission, as detailed in the box above based on The National.
Worked example: financing AED 1.5M in Al Bahyah, from down payment to rent
For an AED 1.5M property in Al Bahyah, budget AED 30,000 in cash for the transfer fee; potential gross rent comes to around AED 78,700 a year. That equals a calculated gross yield of 5.2%, before costs and vacancy, based on Bayut data (April 2026).
Our starting point is Sobha City, developed by Sobha Realty: prices from AED 1.5M, handover in December 2029. The district trades at AED 858/sq ft according to Bayut data (April 2026), so this budget buys around 1,748 sq ft.
Watch the loan line: the table applies the 80% cap, a theoretical maximum reserved for a first primary home. For a property bought to let, as here, the bank's offer sets the loan-to-value, and the down payment required may be higher.
| Item | Calculation | Amount |
|---|---|---|
| Entry price | Project page | AED 1,500,000 |
| Transfer fee | 2% of the price (DARI) | AED 30,000 |
| Theoretical maximum loan (first primary home) | 80% of the price, CBUAE cap — for a rented property, LTV set by the bank | AED 1,200,000 at most |
| Minimum down payment (in this theoretical case) | 20% of the price | AED 300,000 at least |
| Mortgage registration | 0.1% of the loan | AED 1,200 |
| Annual gross rent | 1,748 sq ft × AED 45/sq ft/year (Bayut, April 2026) | ≈ AED 78,700 |
The mortgage registration rate comes from the Dari fee schedule, which caps it at AED 2 million per transaction.
The method is simple: compare the annual rent with the annual repayment the bank quotes you. You then see how much of the loan the rent covers, without having to assume a rate.
Developer payment plan or bank mortgage: which to choose?
It comes down to the time between signing and handover. The developer's payment plan spreads payments up to key handover, with no bank interest. A mortgage mainly finances a completed property or the balance due on handover.
A project in mind?
Talk to a Lucretia adviser
Tailored guidance, no obligation.
In our catalogue, handovers range from 2013 to 2031. Two examples show the gap:
- Al-Reeman Gate: from AED 900,000, handover in March 2028. The schedule is short and the monthly effort heavier.
- Al Ghadeer Gardens: from AED 1.9M, handover in December 2030. The schedule is longer, but rental income starts later.
You can also combine the two: follow the payment plan during construction (see our guide to paying through an instalment plan), then a handover mortgage settles the balance. Keep one asymmetry in mind, though. A completed property earns rent from day one. An off-plan property earns nothing until handover.
How off-plan buying works in full (milestones, guarantees, resale) is explained in our guide to buying off-plan in Abu Dhabi.
Does leverage pay off? Gross yields versus the cost of borrowing
Calculated gross yield ranges from 2.4% in Al Jurf Gardens to 6.8% on Al Maryah Island, with a median of 5.7% across 8 districts, according to Bayut series. That is the figure to compare with the cost of your loan.
The decision rule fits in one sentence: borrowing improves returns only if the total cost of the loan stays below the district's gross yield. In Al Jurf Gardens, at 2.4%, leverage is hard to justify. People buy there for the lifestyle or for capital growth instead.
Tax works in favour of repayment. The official UAE portal confirms that individuals pay no tax on rental income. Gross rent can therefore go entirely towards repayments, subject to the tax rules of your country of residence.
Capital growth is the second driver. The median change reaches +6.1% over 12 months across 10 districts, for a median price of AED 1,792/sq ft, according to Bayut data. A rising value improves your loan-to-value ratio over time.
Financing a purchase with the Golden Visa in mind
The 10-year Golden Visa requires a minimum property investment of AED 2,000,000, according to the UAE government portal. Before signing, get confirmation through that portal that the mortgaged portion does count towards the threshold.
Free guide, delivered on WhatsApp
Get our investment guide
Taxation, visas, financing, buying steps: 14 pages sent to your WhatsApp within minutes.
We make no assumptions on this point, and neither should you. The answer changes how much down payment you need.
Among the projects we list, two sit exactly at the threshold:
- Al Ghadeer Parks, developed by Aldar Properties in Al Layyan: from AED 2M, handover in June 2031.
- Pearl Beach View, developed by Advanced Properties in Al Rahah: from AED 2M.
At this price level, the 2% transfer fee comes to AED 40,000. I advise my clients to keep a buffer above the threshold: a discount negotiated at the last minute can push the price just below it.
Where financing fits into the buying process
Financing comes in at two points. First when you set your budget, then at the transfer of ownership, when the mortgage is registered at the same time as the sale. The steps are set out in our guide to the property buying process in Abu Dhabi.
Your borrowing capacity determines which areas are within reach. To compare prices and districts, see our guide on where to invest in Abu Dhabi.
Pre-approval, before you reserve
Ask the bank for pre-approval before reserving. Your reservation will no longer hinge on a possible loan refusal. On the ground, the mistake I see most often is the buyer who pays the deposit and only then starts the mortgage application. They end up negotiating against the clock.
The transfer can be completed without travelling. The ADREC at Your Place service registers a sale or an off-plan sale at the location of your choice for AED 1,000, VAT included. Lucretia points you to the banks and structures suited to your profile, and you can explore the Abu Dhabi market with us.
The pitfalls of property financing in Abu Dhabi
The most common trap is treating gross yield as money in hand. Bayut figures are gross, before costs and vacancy: net yield is lower, and how you handle property management for your Abu Dhabi rental shapes that gap. Build a buffer into your monthly repayments.
A value that moves during the loan
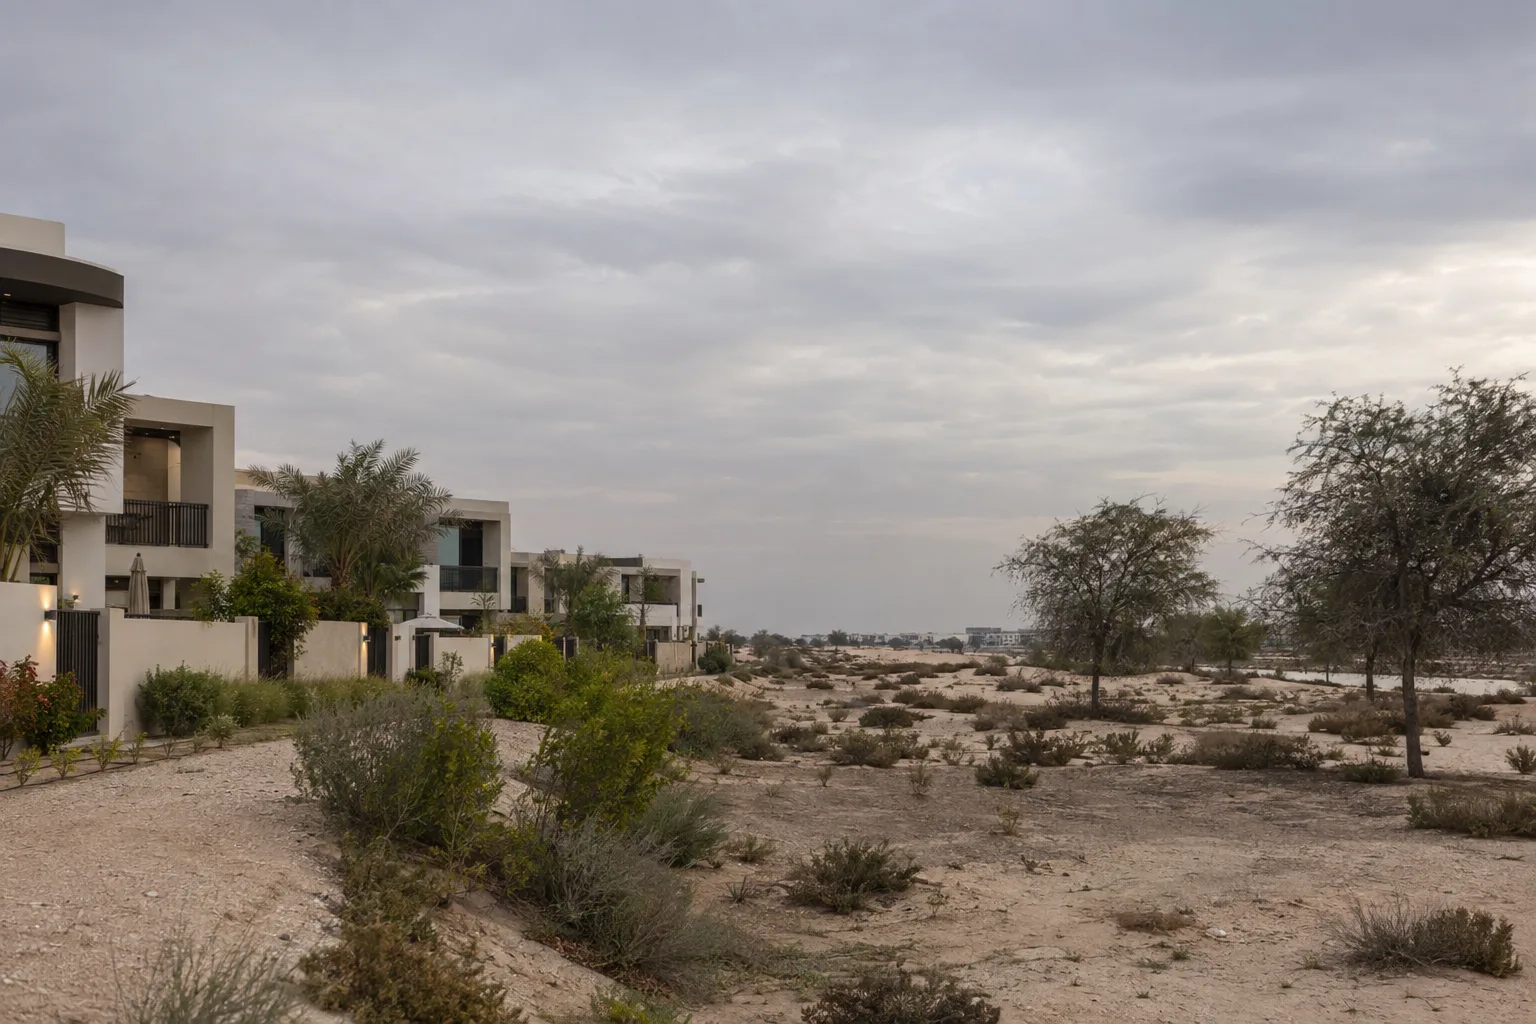
Al Bahyah shows +44.4% over 12 months but −8.6% over 36 months, according to Bayut data (April 2026). These swings directly affect the bank's valuation and what you keep at resale once the loan is repaid.
No rent series, no leverage calculation
Fahid Island trades at AED 3,844/sq ft (March 2026), but Bayut publishes no rent series there. Under those conditions, there is no way to calculate how much of the repayments the rent would cover.
Paying twice at once
Until handover, the off-plan payment plan comes on top of your rent or an existing loan elsewhere. With Hudayriyat Golf Estates, handed over in August 2030, that double burden lasts several years.
Among my clients, the solid financing plans are the ones that would hold up even if the property sat empty for a few months. I always run the numbers without the rent before running them again with it.
— Mourad LACHAB, Real Estate Consultant
In this guide
Articles in this guide
This article is part of our guide
Abu Dhabi Property Investment Guide: Buy, Let and Resell with Confidence
About the author
Mourad LACHAB
Real Estate Consultant
Originally from Strasbourg and after ten years in Paris, Mourad moved to Dubai. A former soldier in the French Army for five years, he developed discipline, rigor and a sense of responsibility — qualities he now puts to work for his clients. He started out in Dubai at an English-speaking agency specializing in the secondary market, then joined Lucretia to support French-speaking clients with a 360° view of the market: off-plan, resales, rentals, taxation, etc. A committed and passionate professional, Mourad stands out for his seriousness, transparency and determination. He also practices boxing, a sport that perfectly reflects his mindset.