
A real estate investment of AED 2,000,000 in a freehold zone grants the 10-year Dubai Golden Visa. Here are the exact conditions, timelines and pitfalls.
On this page
- Dubai Golden Visa through real estate: what are the exact conditions?
- How does the application work, step by step?
- How much do you actually need to invest to reach the AED 2M threshold?
- Financing and total budget: can a mortgage help reach the threshold?
- Why does Dubai attract investors seeking long-term residency?
- What are the pitfalls to avoid before targeting the Golden Visa through real estate?
The Dubai Golden Visa through real estate is available from AED 2,000,000 invested in a property located in a freehold zone, granting a renewable 10-year residency (Official UAE Government Portal). Today it is one of the strongest reasons to buy in the Emirates: a title deed becomes a long-term residence permit, with no employer sponsor required.
But you still need to understand exactly what this threshold covers, how the application is filed and which amounts to plan for beyond the purchase price. This guide walks through the conditions, the steps, a worked example by district and the mistakes that prove costly.
Dubai Golden Visa through real estate: what are the exact conditions?
The condition is a real estate investment of at least AED 2,000,000, which opens a renewable 10-year Golden Visa (Official UAE Government Portal). This threshold is uniform and does not vary by district or property type.
The second condition, a prerequisite to any application: the property must be in a freehold zone, where full ownership has been open to foreigners since 2002 (Dubai Land Department). A property located outside these designated zones grants no entitlement, whatever its price.
What the visa covers is broad: a 10-year residency with no employer sponsor, renewable, with the option to sponsor a spouse and children. The holder retains freedom to enter and leave the country, with no requirement of continuous presence.
The AED 2M threshold is assessed on the property value recorded on the title deed, held in the individual's own name. It applies to both new-build and resale. The purchase process itself is detailed in our dedicated guides to buying off-plan and buying in the secondary market.
How does the application work, step by step?
The application goes through the Dubai Land Department's Golden Visa e-service as soon as the title deed reaches a value of at least AED 2M, then continues with the Emirates ID and the medical exam (Dubai Land Department, Golden Visa e-service). The DLD serves as the entry point for the file.
The real timeline to expect
Allow 2 to 4 weeks in total, the time needed to finalise the Emirates ID and the medical exam once the file is complete. The DLD does not publish an official timeframe: this range reflects what we observe on the files we submit, and an incomplete file lengthens it.
The Dubai REST channel and the issuance of the Emirates ID close the administrative process after DLD validation.
How much do you actually need to invest to reach the AED 2M threshold?
Reaching AED 2M requires a smaller floor area the more expensive the district. The table below sets the price per square foot of three districts against the corresponding floor area for a AED 2M ticket.
| District | Price (Bayut data) | Area for AED 2M | Gross yield* |
|---|---|---|---|
| Palm Jumeirah | AED 4,336/sq ft (March 2026) | ~461 sq ft | 4.5% |
| Downtown Dubai | AED 3,454/sq ft (March 2026) | ~579 sq ft | 5.6% |
| Business Bay | AED 2,445/sq ft (February 2026) | ~818 sq ft | 5.8% |
A project in mind?
Talk to a Lucretia adviser
Tailored guidance, no obligation.
The contrast is stark: at Palm Jumeirah the threshold translates into a compact home, whereas in Business Bay the same ticket delivers nearly twice the floor area. It is also possible to combine several properties to reach the AED 2M mark.
*The gross yield in the table divides the district's median annual rent by its median sale price, based on Bayut series (month shown in the price column). Our guides on rental yield and choosing the district go deeper into prices and profitability.
Among the projects we list, some cross the threshold naturally: Montiva by Vida by Emaar Properties, at Dubai Creek Harbour, from AED 2M.
Financing and total budget: can a mortgage help reach the threshold?
Yes, because the Golden Visa threshold is assessed on the property value, not on the down payment. A non-resident typically secures 50 to 75% financing (a 25 to 50% deposit) depending on the bank, with the CBUAE regulatory cap of 80% applying to resident expatriates.
In practice, a AED 2M property that is partly financed remains eligible as soon as its title deed value reaches the threshold. A mortgage does not lower the bar to clear: it simply eases the cash you need to commit.
The costs to budget on top of the price
- DLD transfer fee: 4% of the price (Dubai Land Department), i.e. AED 80,000 on a AED 2M property.
- Fixed DLD charges: roughly AED 4,700 to 5,500 on top (title deed, plan fees, trustee office), according to Property Finder market data.
- Agency fees in the secondary market: 2% of the price + 5% VAT, payable by the buyer (RERA framework).
On a AED 2M resale purchase, these items add up: the real budget therefore exceeds the purchase threshold. On off-plan bought from the developer, there is usually no buyer-side commission.
Why does Dubai attract investors seeking long-term residency?
Dubai combines a 10-year residence permit with 0% taxation for individuals: no tax on rental income or capital gains (Official UAE Government Portal), and 0% VAT on residential property. Our tax guide details this framework. This legal security, full freehold ownership and zero tax are precisely what tip the scales when you weigh up Dubai against Bali as investment markets.
The market also offers depth, with a median price of AED 1,883/sq ft across 73 districts (Bayut data, most recent point August 2026). So across every price segment, you can find a property that clears the AED 2M threshold in the profile you are targeting — from a high-end studio to a family-sized home.
With my clients, the tipping point is almost never yield alone: it is realising that a single purchase secures both an asset and a right of residence for the whole family. It is that combination that swings the decision.
— Benoit CLAUDEL, Director of Strategy & Operations
For the overall view of the market and strategy, our complete investment guide covers all the parameters.
What are the pitfalls to avoid before targeting the Golden Visa through real estate?
The first pitfall is confusing the negotiated price with the value that counts: it is the value recorded on the title deed, derived from the DLD valuation, that matters for the AED 2M threshold, not the marketing figure. A property bought "around" AED 2M may end up valued below it.
Featured
View projects: Six Senses Residences
From AED 10,259,700
Hand-picked new properties with end-to-end expert support.
View projects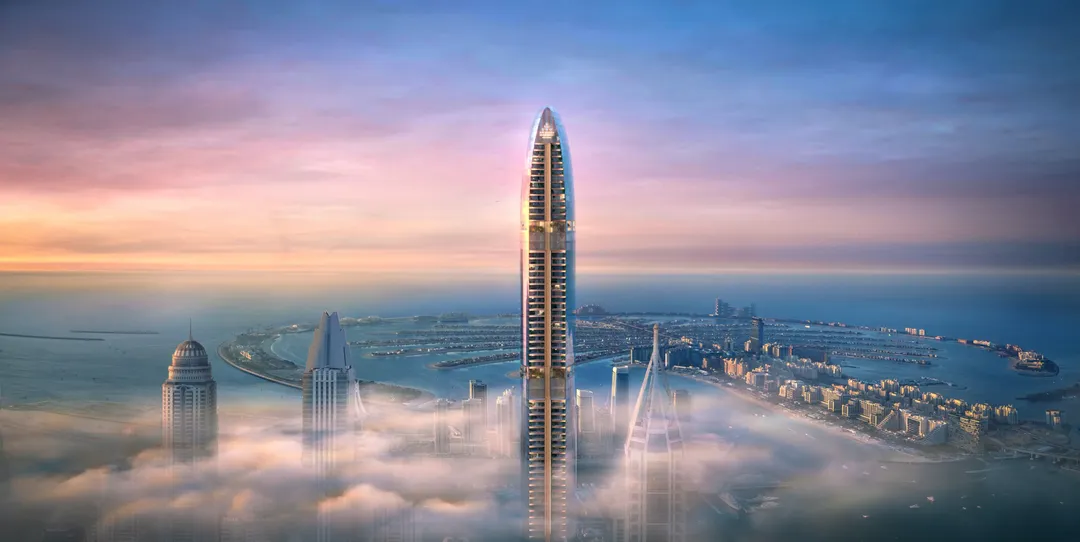
- Poorly timed off-plan: targeting the visa on an unfinished property without checking the eligibility of the provisional title deed (Oqood) at the time of filing. Funds are secured by a mandatory escrow account (Law No. 8 of 2007, RERA/DLD supervision).
- Overlooked holding costs: annual service charges range from around AED 3 to 30/sq ft/year, regulated via RERA's Mollak system. They weigh every year on the property that carries your visa.
- Neglected succession: by default, Sharia law may apply. A registered will (DIFC Wills) secures the transfer of the property for non-Muslims (DIFC Courts).
One final trap, the one about numbers: never confuse the market median price with the price of a specific district. To calibrate your purchase, rely on the Bayut series for the target district, available on each of our district pages. Lucretia supports the Golden Visa application tied to the acquisition, from selecting the property to filing the file.
This article is part of our guide
Dubai Property Investment Guide for Foreign Buyers
About the author
Benoit CLAUDEL
Director of Strategy & Operations
With over 18 years of experience in real estate and wealth management, Benoît has developed recognized expertise in advising private investors, business executives and family offices. After starting out in a real estate agency and working within one of the most reputable wealth management firms in Paris, he then joined LCL as Head of Private Banking for Île-de-France, advising high-income clients on their real estate strategies. An entrepreneur, he founded and ran his own wealth management firm for 7 years, structuring investment and wealth optimization solutions. Today at Lucretia, Benoît oversees operational strategy, sales performance and advisor training. He works on high-value-added cases, particularly investments via French holding companies, legal structuring and wealth taxation.





