How to organise payment for a Dubai property from a European account: the transfer route, choosing the FX channel and preparing proof of source of funds.
On this page
- How to pay for your Dubai property from Europe: the transfer route in four steps
- Do you need to open a bank account in the UAE, and how do you choose the transfer channel?
- Worked example: how much do FX and transfer cost on a 1.2M AED purchase
- Which supporting documents do you need for the transfer to pass banking compliance?
- Why a traced bank transfer is the norm in Dubai
- Watch points and pitfalls of the transfer, the FX and the paperwork
Yes, you can settle a Dubai property with a bank transfer for a real estate purchase from a European account, provided every flow is traceable: off-plan, the funds go to the developer's regulated escrow account, mandated by Law No. 8 of 2007 under RERA/DLD supervision (Dubai Land Department), while in the secondary market settlement happens at the moment of transfer at the DLD. No cash payment, no informal channel: traceability is what makes the purchase valid.
The challenge isn't sending the transfer, it's orchestrating the order of payments, keeping the EUR→AED conversion cost under control, and preparing the supporting documents the Emirati bank requires before crediting the account. We manage these purchases entirely remotely for our European clients, and experience shows the friction almost always comes from the timeline and the paperwork, never from the transfer itself.
How to pay for your Dubai property from Europe: the transfer route in four steps
Paying for a Dubai property follows a traced banking route: a SEPA or SWIFT transfer from your European account to a regulated recipient account, never cash. The destination changes depending on the type of purchase.
Off-plan, the funds go to the project's escrow account. The money is not handed directly to the developer: we break down this mechanism in our guide to the Dubai escrow account.
In the secondary market, settlement takes place on the day of transfer at the DLD, through the trustee office, which charges 4,000 to 4,200 AED (Property Finder). The seller is then paid with a manager's cheque in AED, a locally issued bank cheque. Hence a constraint: your international transfer must arrive beforehand in a local account so that cheque can be issued on the day.
The order of payments
- Reservation: down payment of 5 to 20% of the price (often 10-20%) paid into escrow (market sources SBA/Grosvenor).
- Following instalments: as per the developer's schedule, without re-covering the payment plan here.
Do you need to open a bank account in the UAE, and how do you choose the transfer channel?
A local UAE account isn't essential to pay, except in two cases: issuing the manager's cheque required at the DLD transfer in the secondary market, and repaying a local mortgage. For an off-plan purchase settled directly into escrow, your European account is enough. When issuing the manager's cheque or signing at the DLD would otherwise require your presence, a mandate lets a trusted representative act for you: we detail this in our guide to buying in Dubai remotely with a power of attorney.
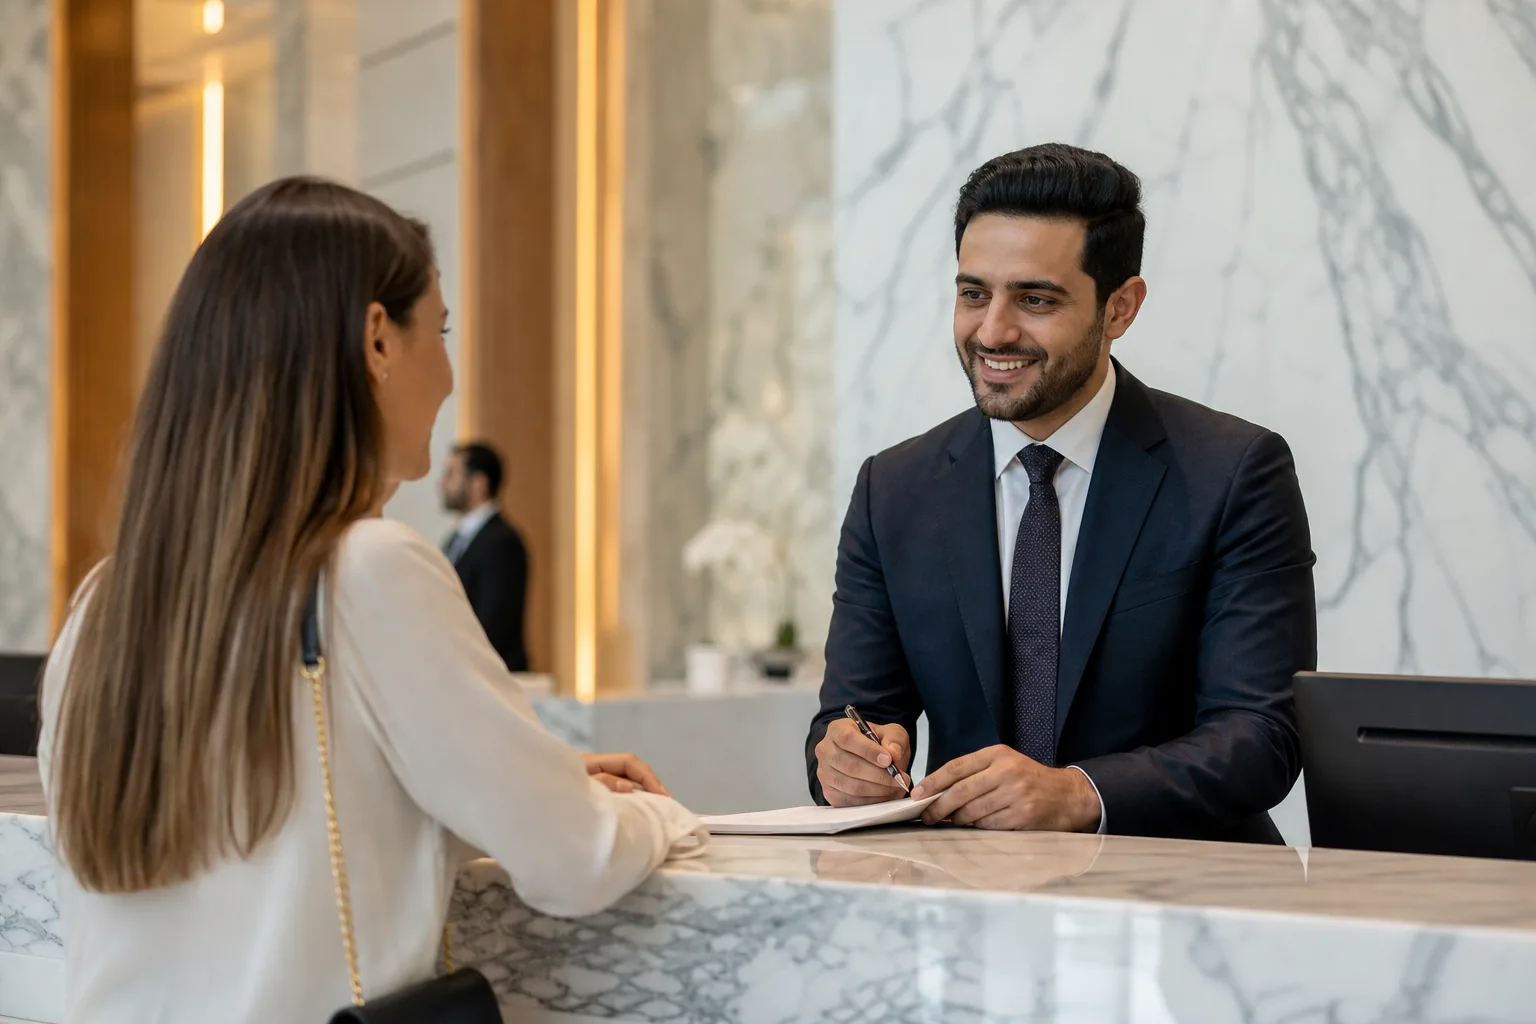
The transfer channel weighs heavily on the amount actually received. A standard SWIFT bank transfer often applies a high FX spread, whereas specialist platforms such as Wise or Currencies Direct offer a rate closer to the interbank rate with clear fixed fees. On six-figure sums, the spread gap runs into thousands of euros.
Comparing EUR→AED transfer channels
Each channel is judged on three criteria: the spread applied to the interbank rate, the transparency of the fees, and the settlement time.
| Channel | FX spread | Fees | Typical use |
|---|---|---|---|
| SWIFT bank transfer | High, often opaque | Fixed fees + correspondent banks' cut | Single large sum via your usual bank |
| Specialist platform (Wise, Currencies Direct) | Close to interbank | Clear fixed fees | Optimised FX, credited amount known in advance |
| Conversion on arrival by the Emirati bank | Often unfavourable | Built into the rate | Best avoided if the net amount in escrow must be precise |
Cascading SWIFT fees and timelines
A SWIFT transfer passes through one or more correspondent banks, each of which may take its cut. The fee option you choose changes the outcome:
- OUR: the sender pays all fees, the beneficiary receives the full amount.
- SHA: shared fees, the correspondent bank takes its share along the way.
- BEN: the beneficiary bears everything, the credited amount is reduced.
Choose OUR if the contract requires a precise net amount in escrow. Allow several business days for an international transfer to the UAE: always plan ahead relative to the DLD transfer date or the off-plan instalment, otherwise a delayed credit can push the entire timeline back.
Worked example: how much do FX and transfer cost on a 1.2M AED purchase
On a 1.2M AED ticket — the median of the 107 priced projects in our catalogue — the EUR→AED conversion cost depends directly on the spread applied, and it comes on top of the local DLD fees. It's often the most underestimated line item in a remote purchase.
Featured
View projects: Keturah Reserve
From AED 3,871,000
Hand-picked new properties with end-to-end expert support.
View projects
The spread is the margin the bank or platform adds to the interbank rate. On 1.2M AED, a 1% spread gap means 12,000 AED of difference on the FX alone — roughly the order of magnitude of much of the DLD's fixed fees. That's why it pays to compare channels before you send.
On top of this FX come the local DLD fees: 4% of the price for the transfer plus the fixed fees — title deed around 580 AED, plan fee around 250 AED, trustee office 4,000 to 4,200 AED (Property Finder), close to 4,800 to 5,000 AED in total. We detail them in our guide to the cost of buying property in Dubai.
Staged payment across several transfers
On a project like The Archive by Imtiaz Developments, in Dubailand Residence Complex from 700,000 AED, the price doesn't go out in a single flow: the reservation down payment and then each instalment give rise to a separate transfer. Every send carries its own FX cost — all the more reason to lock in a competitive channel from the outset.
Finally, in the secondary market, the agency fees (2% + 5% VAT, payable by the buyer) are settled by a separate transfer. Never confuse them with the property payment: these are two flows, two beneficiaries, two sets of supporting documents.
Which supporting documents do you need for the transfer to pass banking compliance?
The Emirati bank receiving the funds, like the European bank sending them, runs KYC/AML checks and requires proof of the source of funds before crediting the account. An incomplete file gets the transfer rejected or frozen.
Prepare in advance the documents that show where the money comes from:
- Proof of savings (bank statements), the deed of sale of a previous property, or any document explaining how the capital was built up.
- Employment contract and tax assessment, to tie the funds to declared income.
Documents that link the transfer to the purchase
The transfer must match the beneficiary named in the contract. Gather the SPA for off-plan or the MOU (Form F) in the secondary market, the reservation receipt, and the escrow account details.
If the property reaches 2,000,000 AED, a traced bank transfer makes it easier to build the residency file: the Golden Visa through real estate requires proof of investment, and a clean bank flow answers that directly.
Why a traced bank transfer is the norm in Dubai
The bank transfer is the norm in Dubai because the entire purchase framework rests on the traceability of funds, from ownership rights through to buyer protection. Three reasons make it mandatory.
First, freehold ownership, open to foreigners since 2002 in the designated zones, which lets a European buyer own and therefore finance a property — the framework is developed in our guide to freehold in Dubai. Second, the off-plan escrow requirement, created by Law No. 8 of 2007 under RERA/DLD supervision, which imposes a banking route rather than a cash settlement.
Third, taxation: individuals pay 0% tax on rental income and capital gains (official UAE government portal). No withholding hits incoming funds, but their traceability is required on entry.
For a French tax resident, the France-UAE treaty of 19 July 1989 (BOFiP) assumes the amounts transferred are consistent with your declared situation. A clean, documented transfer isn't a formality: it's what aligns the purchase with your tax residency.
Watch points and pitfalls of the transfer, the FX and the paperwork
The main risk of a staged payment isn't compliance but FX: a payment plan spread over two to three years exposes your instalments to EUR/AED volatility. Since the AED is pegged to the dollar, your real exposure is to the euro-dollar pair.
Free resource
Get our investment guide
The essentials — strategy, taxation, steps — to download.
Here are the pitfalls that cost the most:
- Hidden fees. An unfavourable FX spread from the bank, a correspondent bank's deduction, rejection fees when the transfer's purpose is incomplete: each one eats into the amount received.
- Vague purpose. A reference that doesn't clearly link the transfer to the contract triggers a request for justification, or even a return of the funds.
On the wealth side, declare the accounts you hold abroad and make sure the flows are consistent with your tax residency — rental income taxation is covered in its own guide. To organise everything from Europe, our support covers end-to-end buying in Dubai.
This article is part of our guide
Dubai Property Investment Guide for Foreign Buyers
About the author

Belen ALBA
Real Estate Consultant
With experience in Dubai's real estate market and an international background between Brussels and Dubai, Belen brings a 360° vision of the sector. After working for more than a year within a well-known developer, she supported both investor clients and partner agents, giving her a unique inside view of the sales process and off-plan projects. Multilingual (French, Spanish, Portuguese and English), Belen knows how to naturally connect with clients from all over the world. Her approach: direct, transparent and results-oriented — with a genuine passion for helping each client make the right investment at the right time.